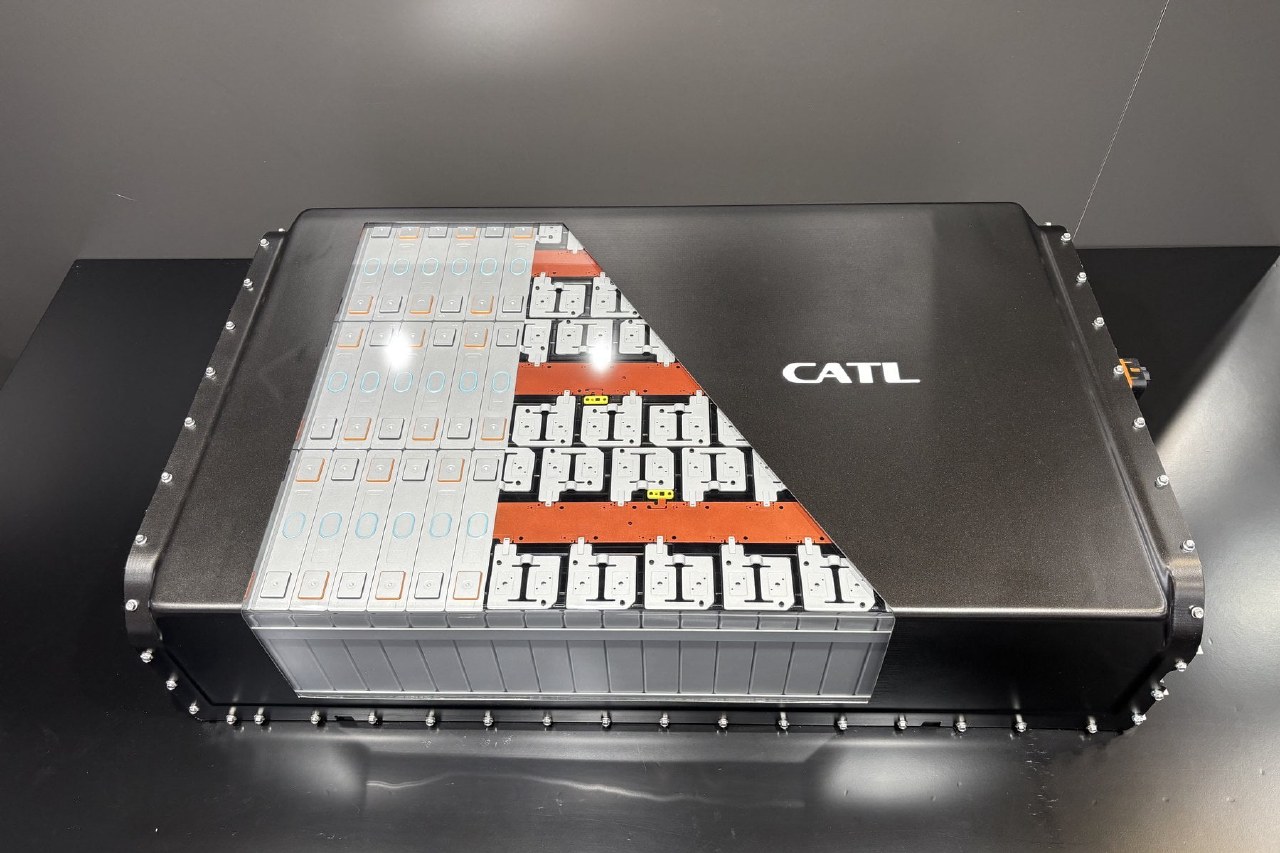
Chinese battery manufacturers now control over half of the global market for electric and hybrid vehicles outside of China. According to SNE Research, the total capacity of these batteries reached 426.7 GWh in the first nine months of the year, marking a 24.7 per cent increase compared to the same period in 2023.
The combined market share of six major Chinese firms, including CATL and BYD, rose from 43.1 per cent to 56.4 per cent. CATL remains the market leader with a 33.7 per cent share, having achieved a volume of 143.7 GWh. BYD secured the third position with 45.9 GWh, representing a 67 per cent year-over-year growth.
In contrast, Korean suppliers LG Energy Solution, SK On, and Samsung SDI saw their combined market share drop from 38.2 per cent to 26.5 per cent. Their total output outside China fell by 13.5 per cent to 113.0 GWh, largely due to a significant decline in North American demand, where their installed capacity nearly halved.
Panasonic, ranking fourth, recorded 35.6 GWh, a slight decrease of 0.8 per cent. The company's market share fell to 8.4 per cent. Meanwhile, second-tier Chinese suppliers such as SVOLT, CALB, and EVE Energy reported triple-digit growth rates, further cementing the dominance of Chinese technology in the sector.
Analysts attribute the shift to the rising adoption of LFP battery chemistry, where Chinese manufacturers hold a competitive advantage. The LFP share in the non-China market grew from 15.8 per cent to 27.7 per cent, driven by demand for price-competitive entry-level vehicle models in Europe and Asia.