Investment bank TD Cowen has initiated coverage of SpaceX with a Buy rating and a price target of $200 per share. This target suggests a potential upside of approximately 35% compared to the closing price of $148.68 recorded on September 25.
The bank forecasts significant growth in total company revenue, projecting an increase from $18.7 billion in 2025 to $40.9 billion in 2026, and reaching $113.2 billion by 2027. EBITDA is also expected to rise from $6.6 billion in 2025 to $60.8 billion in 2027.
The primary driver for these projections is AI compute leasing. Analysts expect this segment to account for 35% of total revenue in 2026 and grow to 60% by 2027. Revenue from this service is forecast to climb from $14 billion in 2026 to $133 billion by 2028.
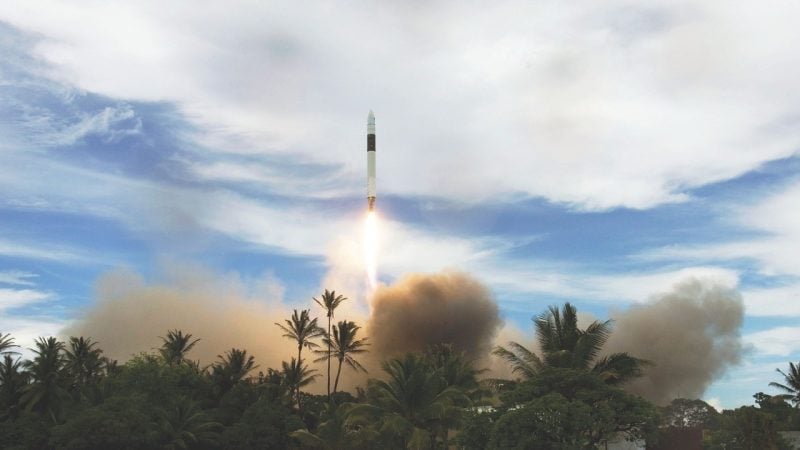
SpaceX plans to dedicate over 85% of its future launch capacity to internal operations, specifically supporting Starlink and orbital data centers, rather than focusing on third-party contracts. Analysts note that building orbital data centers involves significant execution risks, including hardware maintenance challenges and latency issues.