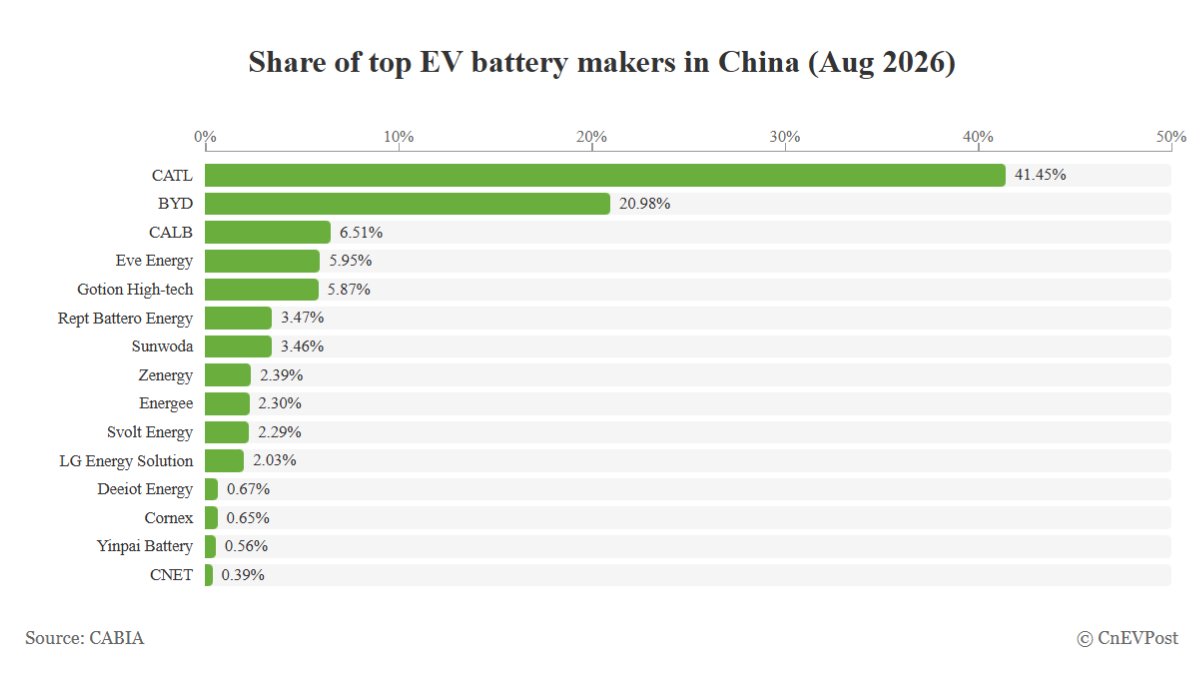
In August 2026, China's power battery installations reached 79.0 GWh, marking a 26.3% year-on-year increase. CATL maintained its leadership with a 41.45% market share and 32.54 GWh of installations, despite a slight decline from its 42.33% share in July.
BYD secured the second position with 16.47 GWh, representing a 20.98% market share. The gap between CATL and BYD narrowed to 20.47 percentage points. Together, the two companies controlled 62.43% of the domestic market.
CALB ranked third with a 6.51% share, followed by Eve Energy at 5.95% and Gotion High-tech at 5.87%. The top five manufacturers collectively accounted for 80.76% of the total market volume.
The ternary battery segment saw a decline to 11.0 GWh, representing 14.0% of total installations. CATL led this segment with a 66.80% share, while LG Energy Solution moved into second place with a 14.50% share.
LFP battery installations grew to 67.6 GWh, capturing a record 85.6% of the market. CATL held a 37.31% share in this segment, while BYD followed with 24.41%. The gap between the two in the LFP market decreased to 12.90 percentage points.