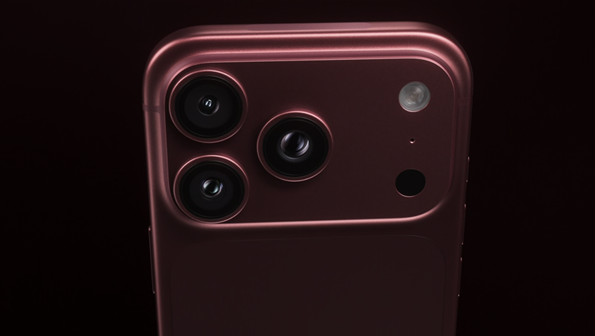
Apple has unveiled the iPhone 18 Pro series and its first foldable device, the iPhone Duo. The latter is positioned as a premium, low-volume product with a starting price of $1999. Analysts at Morningstar expect this pricing strategy to drive double-digit revenue growth for the iPhone segment in fiscal 2027, despite projections that total unit sales will remain flat.
Profit margins remain a primary concern for Wall Street. Analysts note that rising memory and hardware costs are expected to compress Apple's gross margin by over 1 percentage point in fiscal 2027, with a potential recovery anticipated by fiscal 2028. Jefferies highlighted that the modest $100 price increase for the 18 Pro models, lower than the previously expected $100–200 range, may further impact profitability.
Market reactions to the launch are mixed. Jefferies maintains an underperform rating, citing concerns over pricing strategy, while Lynx Equity downgraded the stock due to supply chain risks involving memory and flash storage. Conversely, HSBC and Evercore ISI remain optimistic, setting target prices of $366 and $365 respectively, suggesting a potential upside of approximately 16% from the current price of $315.
KeyBanc analysts warned that the high price points of the new lineup might fail to offset margin pressures, potentially leading to lower shipment volumes and slower growth in the services business. Meanwhile, Morningstar raised its target price for Apple from $285 to $290, though it maintains that the stock remains slightly overvalued relative to its current market performance.