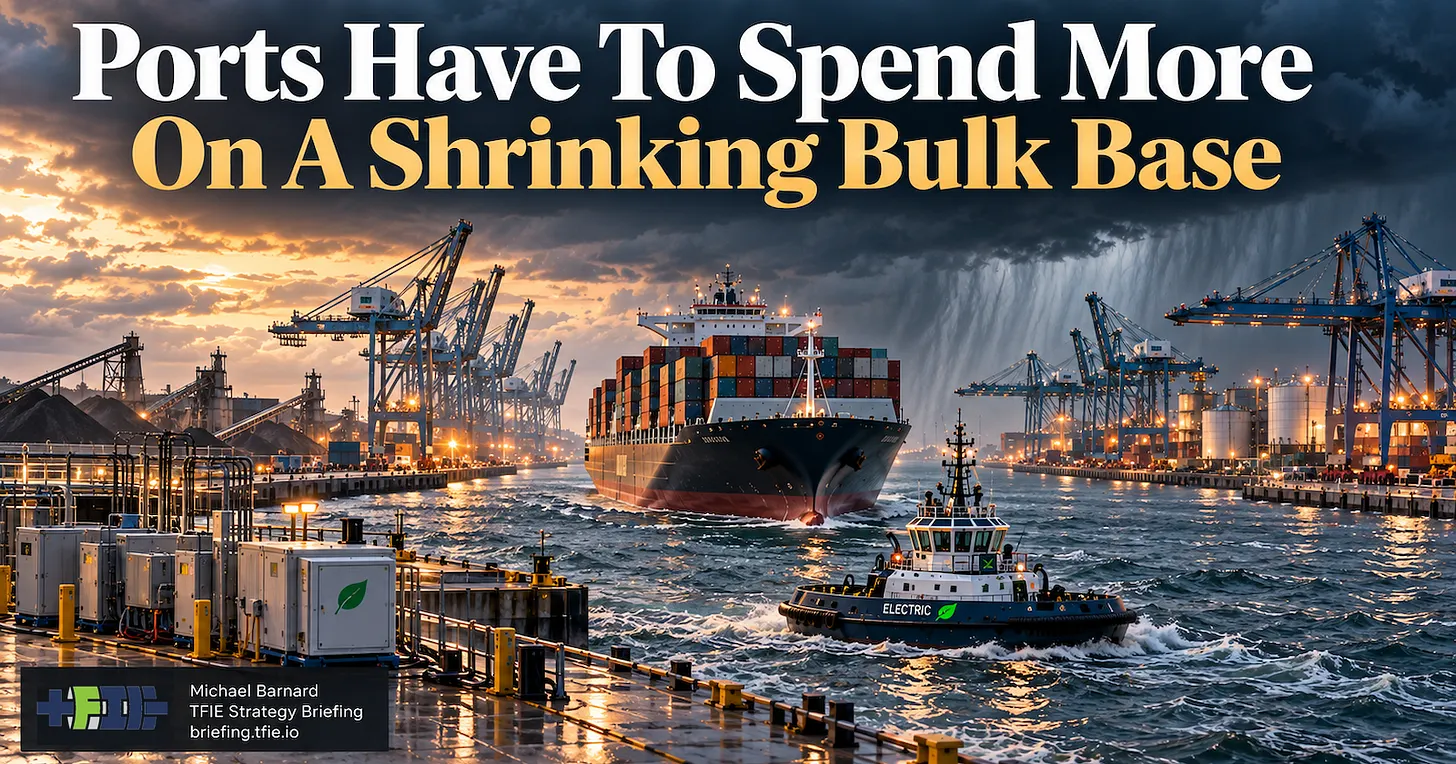
Global ports face a significant capital challenge as traditional bulk cargo volumes, which historically funded infrastructure, enter a structural decline. Currently, coal, oil, and petroleum products account for approximately 40% of maritime freight tonnage, while iron ore contributes another 15%.
Electrification is reducing the demand for fossil fuel shipments, while shifts in steelmaking and increased scrap usage are impacting iron ore trade. Simultaneously, ports must invest in deeper channels, larger cranes, and more robust tug fleets to accommodate larger vessels, alongside rising costs for climate resilience.
Port authorities are attempting to offset these losses by targeting new markets, such as hydrogen, ammonia, methanol, and biofuels. However, analysts note that not all ports can simultaneously capture market share from competitors or successfully replace lost fossil fuel volumes with new commodity flows.
The TFIE Strategy Briefing suggests that electrification offers a versatile investment path because electric cranes, yard equipment, and battery-electric tugs remain functional regardless of the specific cargo mix. Shore power and grid upgrades provide a foundation that supports various future operational scenarios.
While ports must decide which legacy assets to retire or convert, experts argue for prioritizing durable shared infrastructure. Investments in grid connections, substations, and rail interfaces can lower operating costs and emissions across multiple freight futures, reducing the risks associated with long-term cargo forecasting.