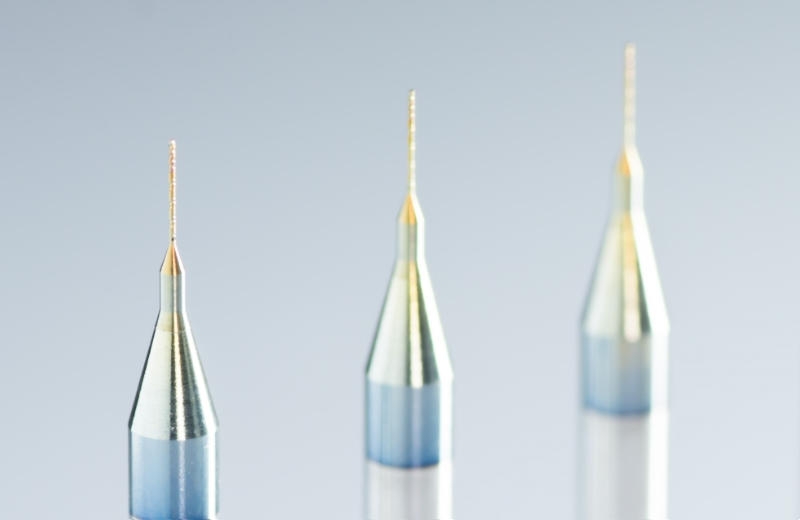
China's export restrictions on tungsten have caused a global shortage and price surge for micro-drills, which are essential for manufacturing AI chip substrates and printed circuit boards. These tools, made from tungsten carbide, are critical for creating high-precision micro-holes in increasingly complex chip architectures.
Major global manufacturers like Sumitomo Electric, Kyocera, Mitsubishi Materials, Kennametal, and Sandvik rely heavily on Chinese tungsten supplies. Meanwhile, Chinese firms such as Guangdong Dtech Technology and Shenzhen Jinzhou Precision Technology have gained market share, with Dtech reporting a 180% sales increase and a 280% profit jump for the third quarter.
China controls approximately 79% of global tungsten production. The price of ammonium paratungstate, a key benchmark, rose from ¥212,750 per ton in February 2025 to over ¥530,000 currently. International prices are reportedly even higher, reaching up to ¥1.8 million per ton.
To mitigate supply chain disruptions and bypass export controls, many manufacturers are increasingly integrating Chinese materials or relocating production facilities directly into China. This follows previous restrictions on germanium and quartz, which impacted the aerospace and optical industries.