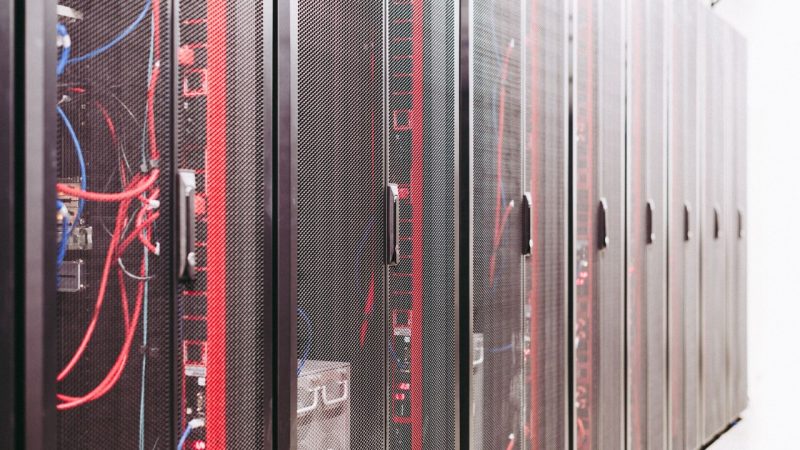
In July 2026, private spending on data center construction reached a seasonally adjusted annual rate of $75 billion, marking a 57% increase compared to the previous year. This surge contrasts with the broader private construction market, which totaled $2,16 trillion in July, reflecting a 0.5% monthly decline and a 3.8% drop year-over-year.
Data centers are currently the primary driver of growth in the nonresidential construction sector. In 2025, the total value of construction starts for these facilities reached $77,7 billion, representing a 190% increase over 2024 figures. Major technology firms including Amazon, Google, Microsoft, and Meta are driving this demand through massive annual capital expenditure plans.
High demand is evidenced by pre-leasing rates exceeding 80% for new facilities. However, the industry faces a significant bottleneck due to electricity supply constraints. In Texas alone, there are over 1,800 interconnection requests totaling more than 474 gigawatts, while the total installed capacity of the entire US electrical grid is approximately 1,300 gigawatts.
The process of connecting new data centers to the power grid can take several years in certain markets. Despite these infrastructure challenges, the outlook for data center REITs and related infrastructure investments remains positive, supported by deep construction backlogs and high pre-leasing activity.