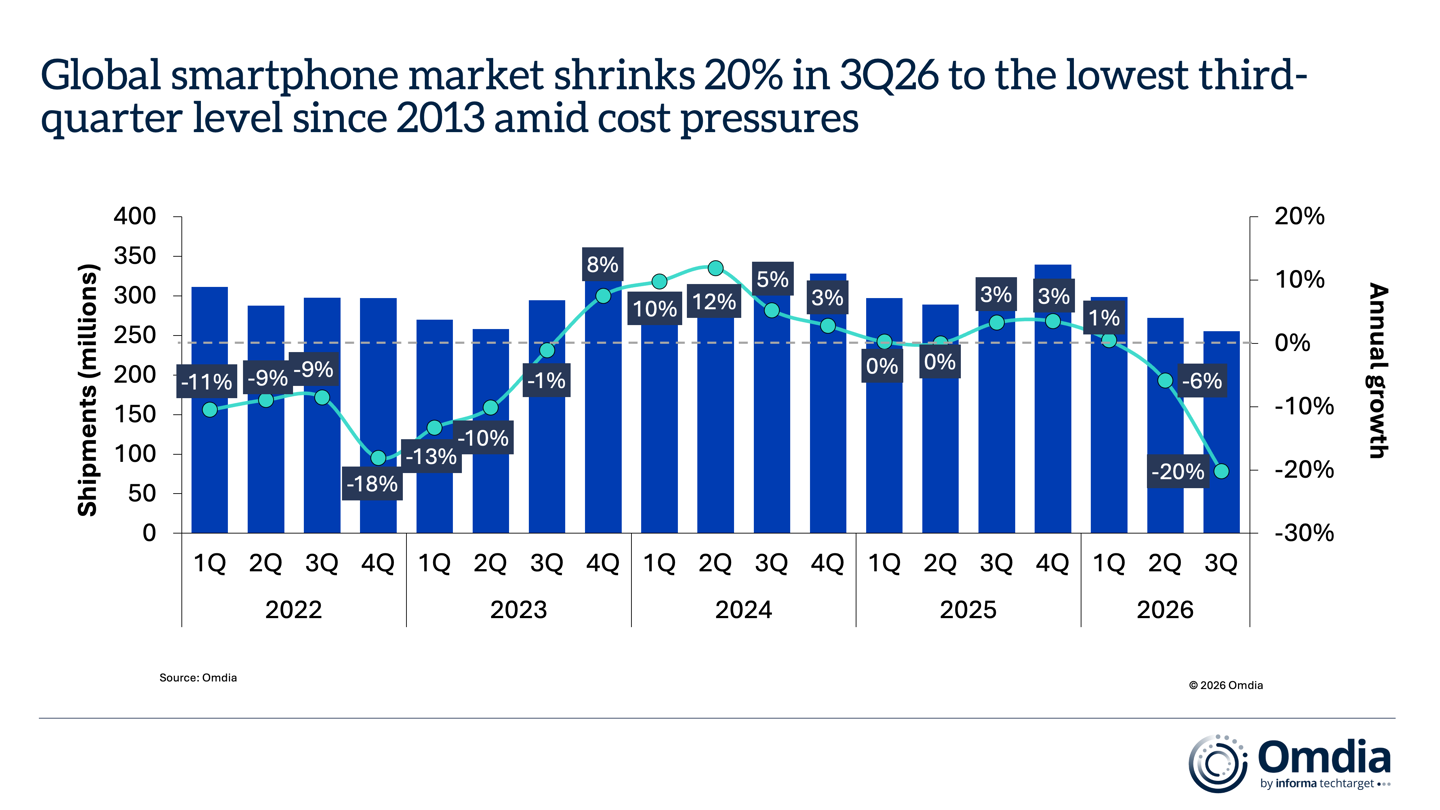
According to preliminary data from Omdia, global smartphone shipments declined by 20% year-over-year in the third quarter of 2026. This drop represents a significant acceleration in the market downturn compared to the 6% decline observed in the second quarter.
Despite the launch of several flagship devices during the third quarter, the market also experienced a sequential decline in shipments. Analysts attribute this trend to persistent memory cost pressures, which have limited pricing flexibility for manufacturers.
To maintain profitability, smartphone brands are prioritizing average selling price growth and product portfolio optimization. Companies are increasingly cutting shipments of low-margin devices to mitigate the impact of rising component costs on their bottom lines.
The market is seeing increased polarization, with Samsung and Apple leading the industry with 23% and 22% market shares, respectively. Their combined share has risen by 8 percentage points compared to the same period last year.
Following the two market leaders, Xiaomi holds a 12% share of global shipments, while OPPO and vivo account for 9% and 8%, respectively. These figures reflect the ongoing consolidation of the smartphone sector among top-tier manufacturers.