

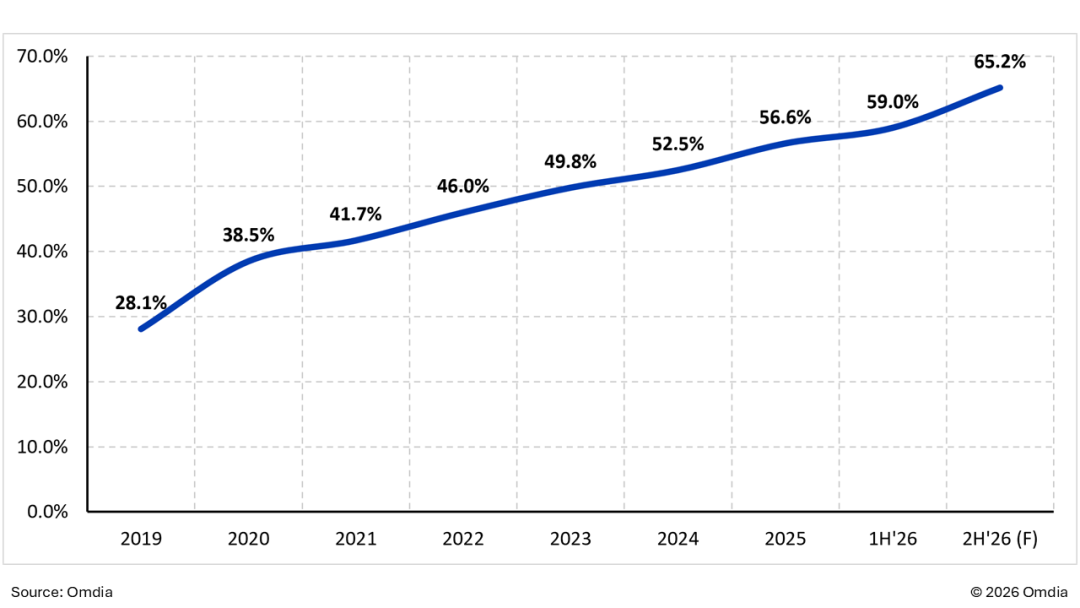
China's panel manufacturers will likely dominate the global automotive display market by 2026. According to Omdia, their market share is projected to reach 65.2% in the second half of 2026, up from 59% in the first half of the same year.
The growth reflects a long-term structural shift. The market share of Chinese manufacturers has increased from 28.1% in 2019 to an estimated 56.6% in 2025.
The shift is driven by low returns on mature LCD lines outside China, leading other manufacturers to close or sell their facilities. Consequently, the number of commercial a-Si/Oxide LCD lines outside mainland China may drop from seven in 2026 to three by 2028.
China continues to invest in G8.x OLED capacity, including BOE B16, TCL CSOT T8, and Visionox V5. As these high-generation lines prioritize smartphones and IT displays, more G6 OLED capacity will be freed up for automotive projects.
A significant portion of G6 OLED capacity that began ramping up around 2020 will have completed depreciation by 2028, which is expected to lower costs and increase the competitiveness of OLED in cars.